On this page
A car moving between a family home and a Baton Rouge campus raises different questions from a vehicle used every day for work. Start with the actual garaging address, the people who have access to the car and how it is used. This guide helps LSU and Southern students, families sharing vehicles and commuters prepare an accurate coverage comparison.
Key Takeaways
-
Louisiana Car Insurance, operated by Drivers Insurance Agency, Inc., helps Baton Rouge drivers and families compare car insurance options from multiple insurers. Request a quote online or call (844) 454-1313 to start a conversation with a licensed insurance agent.
-
Use the actual address where each car is principally kept, and describe commuting, student use, delivery work and regular drivers accurately. A Baton Rouge mailing address or the words “East Baton Rouge Parish” alone do not establish the right garaging information or predict a premium.
-
Louisiana’s standard private-passenger auto liability minimum is 15/30/25. Bodily injury UM generally matches bodily injury liability limits unless a permitted lower-limit, economic-only or rejection selection is made through the prescribed process.
-
Special Baton Rouge situations-household vehicles shared between parents and students, cars garaged at campus apartments near LSU or Southern, and planning transportation when a car is in the shop-deserve specific attention when building your policy.
-
Plan for transportation while a car is being repaired. Rental reimbursement and roadside assistance serve different purposes and have limits; neither should be assumed to come with liability-only coverage.
-
A quote request does not bind coverage. Always confirm binding, the exact effective date, and time with your agent before canceling any existing policy.
How Baton Rouge Drivers Use Their Cars (And Why It Matters)
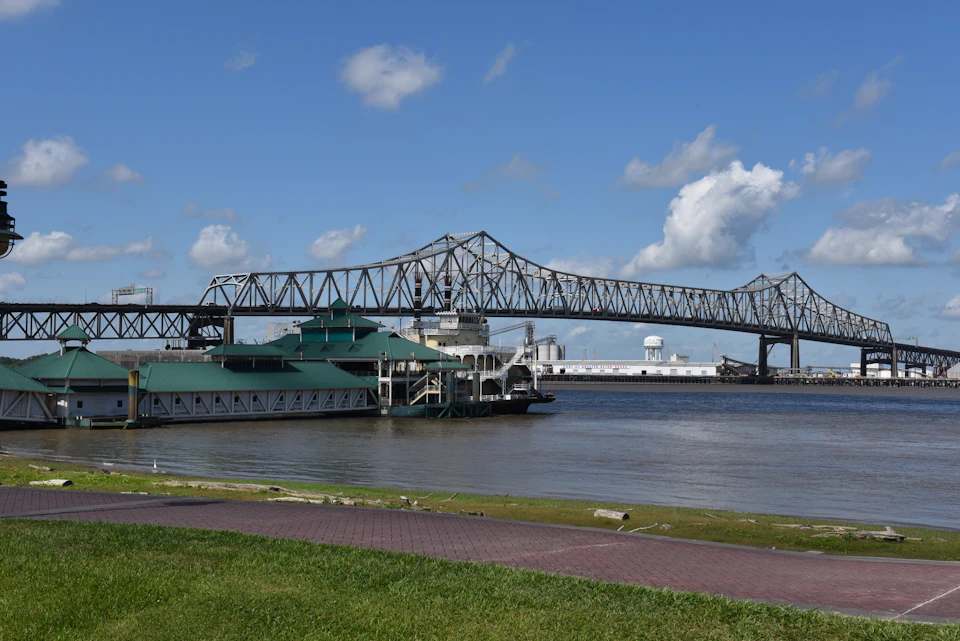
If your routine includes I-10 or I-12, errands on Government Street, or travel to LSU or Southern, describe that actual use when requesting quotes. Estimate mileage as accurately as you can, and update the insurer when your commute or work use changes. A route name is useful context, not evidence of a particular premium or accident rate.
The garaging address is where the vehicle is principally kept, which may differ from a mailing address or a parent’s home. Use the actual street address and confirm how the insurer treats a student living between locations. Do not treat all of East Baton Rouge Parish, including separate municipalities such as St. George, as one city location.
Explain whether the car is used for errands, commuting, visiting clients, delivery or rideshare work. A student apartment near Burbank Drive and a parent’s home are different locations to disclose, but this guide does not rank their insurance risk or prices. Ask how the insurer classifies your specific use before selecting a policy.
Household Vehicles, Named Insureds, and Baton Rouge Families
Tell the insurer about household members and anyone who regularly has access to the vehicles, including family members, adult children or roommates. Policy definitions and listing requirements vary. Do not assume an unlisted regular driver is covered, or exclude a person without understanding the consequences.
The named insured is the person listed on the policy who holds the coverage. Vehicle ownership-whose name is on the title and registration-affects who should be the named insured and can impact how a claim is handled. If a car is titled to a parent but driven daily by a college-age child, those details need to be reflected accurately.
For example, a Mid City family might share two vehicles with a college-age child who returns from campus on weekends. Tell the insurer who owns each car, who keeps it and who regularly drives it. Ask whether the child should remain listed and whether a student classification applies. Do not assume one rule covers every family or insurer.
LSU and Southern Students: Cars, Campus, and Changing Garaging Address
Louisiana State University near Tiger Stadium and Southern University along Scenic Highway draw students from across the state. Many move between dorms, off-campus apartments, and home throughout the year, which creates real questions about where the car is garaged.
What “student away at school” means varies by company. When a student from Shreveport, Lafayette, or another Louisiana city takes a car to Baton Rouge, their policy may need to reflect the new location. If that student signs a lease for an apartment on Nicholson Drive or near Harding Boulevard, the overnight parking location has likely changed-and so has the garaging address. Even if the student returns home on weekends, insurers may require the campus-area address if the car is kept there most of the school year.
If the car stays at the parents’ Baton Rouge home while the student attends school in another city, the policy still needs to list the correct Baton Rouge garaging address where the vehicle is actually parked overnight.
-
Company-specific eligibility, student classifications, and any related savings cannot be guaranteed and must be confirmed with the insurer and your licensed insurance agent.
-
Call your agent when a student signs a new lease or campus housing contract-do not wait until a claim to discover the address is wrong.
Daily Commuters vs. Delivery and Business Use in Baton Rouge
A commute from home to an office or campus differs from using the same car to make paid deliveries or visit customers. Tell the insurer when you travel between home, Baton Rouge and another community. Report changes in mileage and work use instead of choosing the lowest-priced use category without regard to the facts.
Before accepting delivery or rideshare work, ask whether your personal policy covers it and what happens during each app period. Platform insurance may have gaps, conditions or different deductibles. Explain whether the vehicle is used only for commuting or also for paid trips; confirm any endorsement or commercial coverage needed before starting.
Misclassifying use-rating a delivery car as “pleasure only”-can lead to denied claims or policy cancellation. Honest communication is always in your best interest.
What Louisiana Law Requires – Baton Rouge Drivers’ Legal Basics
This section provides general information for private passenger auto insurance and is not legal advice. Laws can change, so verify current rules through official sources or consult an attorney.
For standard private-passenger auto insurance, R.S. 32:900 specifies minimum liability limits of $15,000 bodily injury per person, $30,000 bodily injury per accident and $25,000 property damage per accident. These are separate limits, commonly called 15/30/25.
Liability coverage pays for injuries or damage a covered driver legally causes to others in an accident. It does not pay to repair your own vehicle.
Under R.S. 22:1295, bodily injury UM generally matches bodily injury liability limits unless the named insured makes a permitted lower-limit, economic-only or rejection selection through the prescribed process. Economic-only coverage excludes noneconomic damages. Review the form and actual policy terms rather than treating UM as an ordinary unchecked optional box.
Comprehensive and collision cover damage to your own car, subject to policy terms and deductibles, but they are not required by Louisiana law. Lenders may separately require them on financed vehicles. You can read more about statewide minimums on the minimum car insurance and coverage pages.
Financed Vehicles, Deductibles, and Avoiding Gaps When You Switch
A lender or lease agreement may require comprehensive, collision and specified deductibles independently of state liability minimums. Check the agreement before reducing coverage. If requirements are not met, lender-placed protection may follow; its cost and protection can differ from a policy you select yourself.
Compare deductibles against money you could actually pay after a covered loss. A hypothetical change from a $500 deductible to $1,000 adds $500 to that deductible exposure; any premium reduction must be quoted. Check whether the lender permits the change and compare comprehensive and collision separately.
When switching policies, never cancel an old policy until you have written confirmation that the new policy is issued, bound, and the effective date and time are clearly understood. Requesting a quote or speaking with an agent does not itself create coverage-binding must be explicitly confirmed.
Planning for Repairs and Temporary Transportation in Baton Rouge
A covered accident or hail damage can leave you without a car while it sits in a body shop on Airline Highway or Florida Boulevard. Rental reimbursement coverage, if included in your policy, can contribute toward a rental car or other transportation while the vehicle is being repaired after a covered claim, up to per-day and total limits explained in your declarations page.
Some families coordinate by temporarily sharing a second household vehicle, using Capital Area Transit System (CATS) bus service routes, or carpooling to LSU, Southern, or state office buildings downtown. Think through your backup transportation plan before an accident happens and review whether your current policy includes rental reimbursement. Actual eligibility and limits depend on your specific insurer and policy-speak with your agent to confirm.
Comparing Baton Rouge Car Insurance Options with Louisiana Car Insurance
Louisiana Car Insurance, operated by Drivers Insurance Agency, Inc., helps drivers discuss available auto coverage options. Ask which insurers and policy choices are being considered for your situation. No fixed carrier count, savings amount or lowest-price guarantee is offered here.
Ask about discounts for which you may qualify and the documentation required. A student classification, multi-policy arrangement or usage-based program is not an automatic saving. Compare the final cost and terms, and review what information a telematics program collects before choosing it.
Request a quote online to get started. Call (844) 454-1313 with coverage questions or use the quote comparison guide to prepare. This page describes a service area, not a Baton Rouge walk-in office. A request does not bind insurance.
Official Baton Rouge Road and Emergency Resources
Check current official information before traveling. These resources support route planning; they do not establish a neighborhood’s insurance price or guarantee a safe route:
-
City-Parish road closures — The Traffic Engineering Division maintains a listing of current and planned closures with links to details. Check it for updates instead of relying on a dated list in an insurance article.
-
Louisiana 511 traveler information – 511la.org/map offers the latest traffic incidents, construction, and travel conditions for I-10, I-12, and US-190.
-
City-Parish emergency alerts — Check official notices and follow instructions from local officials. This guide does not report a live emergency status.
These tools help with situational awareness but do not replace safe driving habits or the need for appropriate insurance coverage.
Sample Comparison Checklist for Baton Rouge Auto Insurance Policies
Use this table to line up two or three quotes side by side. The lowest price is not always the best fit if it comes with much lower limits or missing UM coverage.
|
Coverage Detail |
Policy A |
Policy B |
Policy C |
|---|---|---|---|
|
Bodily injury liability (per person / per accident) |
|||
|
Property damage liability limit |
|||
|
UM/UIM limits (or rejected/reduced?) |
|||
|
Comprehensive deductible |
|||
|
Collision deductible |
|||
|
Rental reimbursement (yes/no, daily limit) |
|||
|
Towing / roadside assistance (yes/no) |
|||
|
Business or delivery use included? |
|||
|
All household drivers listed? |
|||
|
Garaging address accurate? |
|||
|
Total premium and policy term |
Use the same policy term and payment assumptions for each column. Mark missing information as “ask insurer” rather than treating a blank as zero or as proof that coverage is included. Louisiana Car Insurance can discuss your comparison at (844) 454-1313.
Frequently Asked Questions – Baton Rouge Car Insurance
These FAQs address common Baton Rouge-specific questions that go beyond the main sections above.
Do I need to change my car insurance if I move from a Baton Rouge dorm to an off-campus apartment?
Yes. Any time your primary residence or where the car is kept overnight changes-moving from an LSU dorm to an apartment on Burbank Drive, or from Southern’s campus to a Scenic Highway rental-contact your insurance agent to update the garaging address and driver information. Failing to update can create rating or claims issues. Each insurer has its own rules for students away at school, so do not assume your current policy automatically adjusts.
My child goes to LSU but their car stays at our Baton Rouge home. How should we list them on the policy?
In many cases, a licensed child who is a household member and regularly has access to the family car should be listed as a driver on the policy, regardless of age or how much time they spend on campus. Discuss frequency of vehicle use, where the car is garaged, and company-specific underwriting rules with your agent so the policy reflects actual exposure.
Can I switch Baton Rouge car insurance companies any time, or do I have to wait for renewal?
You can ask about changing insurers before renewal, but review cancellation terms, fees and any refund with the current insurer. Confirm the replacement is bound and its exact effective date and time before ending existing coverage. Coordinate lender and any SR-22 requirements separately to avoid a gap.
Is minimum liability coverage enough for Baton Rouge commuting on I-10 and I-12?
The standard 15/30/25 limits meet Louisiana’s basic liability minimum, but a covered loss can exceed them on any road. Compare higher limits and decide how you would manage a shortfall. Liability does not repair your own car; consider collision and comprehensive separately and check lender requirements.
How do I get help with a non-owner or SR-22 policy if I drive in Baton Rouge but don’t own a car?
A non-owner policy may suit an eligible driver without a vehicle, but regular access to a household car can affect eligibility. Disclose every vehicle you own or routinely use. If OMV requires an SR-22 filing, confirm your own requirements and dates. A filing does not itself reinstate a license.
Baton Rouge service area
This map identifies Baton Rouge, not an agency office. Use the actual address where each vehicle is principally kept when discussing coverage.