On this page
Key Takeaways
-
Louisiana requires at least 15/30/25 liability limits on most registered vehicles, but many Shreveport drivers benefit from higher coverage plus uninsured motorist protection.
-
Louisiana Car Insurance, operated by Drivers Insurance Agency, Inc., helps Shreveport and Caddo Parish drivers compare car insurance options by phone at (844) 454-1313.
-
Regular trips across the Red River to Bossier City, or into Texas and Arkansas, generally stay within a Louisiana auto policy’s territory-but garaging address, vehicle use, and coverage terms still need careful review.
-
Comprehensive coverage, collision, roadside and towing assistance, and rental reimbursement are especially useful for Shreveport drivers who commute, road-trip, or leave vehicles parked for stretches of time.
-
A quote does not bind coverage; confirm an effective date and time before assuming you are covered.
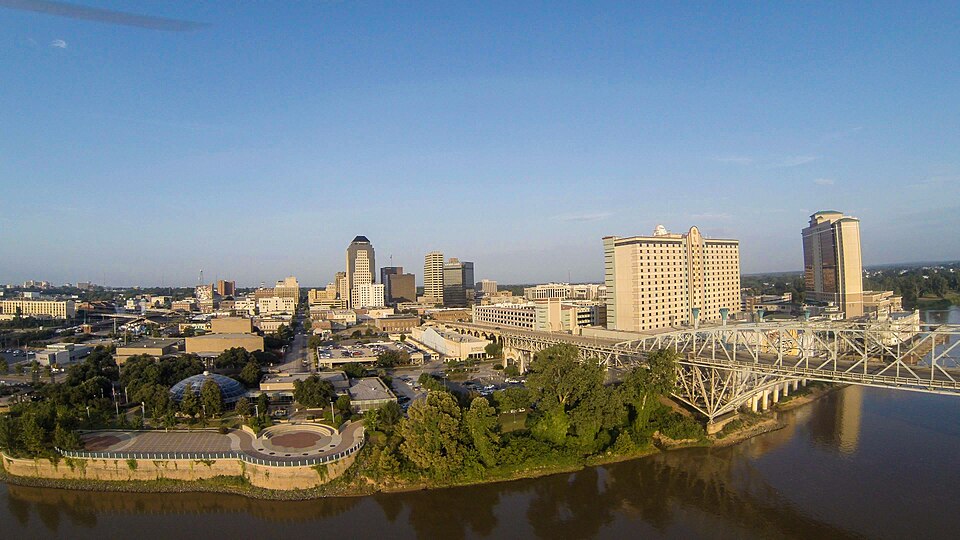

Car Insurance in Shreveport, LA: How We Help
Louisiana Car Insurance is an independent agency serving Shreveport, Caddo Parish, and surrounding areas with practical auto insurance guidance-not just quick quotes.
-
We are operated by Drivers Insurance Agency, Inc. Shreveport drivers can request a quote online or call (844) 454-1313 to review coverage and request quotes.
-
We focus on everyday drivers, commuters crossing the Red River, road-trippers using I-20, I-49, and Youree Drive, teen drivers, and people with tickets, accidents, or lapses in their driving history.
-
We compare coverage options from multiple insurers, explain trade-offs in plain language, and help you find affordable coverage that fits your situation. Insurance agents can help find applicable discounts for drivers in almost every category.
-
A quote does not bind coverage. Confirm that the insurer has bound coverage and verify its effective date and time before driving.
Louisiana Minimum Car Insurance Requirements for Shreveport Drivers
Every person who owns a registered vehicle in Louisiana faces the same statewide rules. Visit our minimum car insurance page for a deeper breakdown.
-
Louisiana law (R.S. 32:900) requires liability insurance on most registered vehicles: at least $15,000 bodily injury per person, $30,000 bodily injury per accident when more than one person is injured, and $25,000 property damage per accident-commonly written as 15/30/25-and that per-accident injury limit can be used up quickly if a crash injures multiple people.
-
Liability coverage pays for injuries and property damage you cause to others. It does not pay to repair your own car after a collision, storm, or theft.
-
Under R.S. 22:1295, bodily injury UM generally matches bodily injury liability limits unless the named insured makes a permitted lower-limit, economic-only or rejection selection through the prescribed process. Review the form and the coverage details before choosing.
-
Driving without required liability can lead to fines, license and registration issues with the Louisiana OMV, and personal financial responsibility after an accident.
-
The standard Louisiana liability minimum is the same in Shreveport as elsewhere in the state. Your actual driving, household finances and vehicle use help determine which additional limits and coverages to compare; a city or state average does not decide that for you.
Going Beyond the Minimum: Coverage That Fits Shreveport Life
The 15/30/25 minimum is a legal floor, not a safety target. Many Louisiana drivers-especially those who commute daily or drive newer vehicles-need more comprehensive protection.
-
Higher liability limits can provide more protection against covered claims after a serious accident. Ask for a comparison that includes limits such as 100/300/100, and consider the financial shortfall you could face if a claim exceeds your limits. No single limit fits every household.
-
Collision coverage can pay for covered damage to your car after a collision with another vehicle or object, subject to the policy and deductible. “Full coverage” is informal shorthand, often including liability, collision and comprehensive; it does not mean every loss is covered. Lenders commonly require collision and comprehensive on financed or leased vehicles.
-
Comprehensive coverage can address covered non-collision losses such as theft, vandalism, fire, falling objects, hail, flood and direct animal strikes, subject to policy terms and deductibles. Discuss these risks before a trip or a period of parking. Repair costs depend on the damage and vehicle; this guide does not assign a fixed price to a deer collision.
-
Optional protections worth considering: medical payments coverage for immediate medical bills regardless of fault, rental reimbursement while your car is in the shop for a covered claim, and roadside or towing coverage for breakdowns on interstate or rural trips.
-
Raising collision and comprehensive deductibles-opting for higher deductibles-can lower monthly premiums, but increases your out-of-pocket cost if you file a claim. Balance the savings against your risk tolerance and vehicle type.
-
Explore our coverage explanations or call (844) 454-1313 to walk through which options fit your budget and vehicle age.
Uninsured Drivers and UM Coverage in Shreveport and Caddo Parish
An uninsured or underinsured at-fault driver can leave an injured person facing a financial shortfall. Review UM coverage before rejecting or reducing it. A statewide statistic or a health-insurance statistic should not be treated as a measured Caddo Parish auto-insurance rate.
-
UM coverage pays for injuries from uninsured drivers, helping with medical bills, lost wages, and related damages when the at fault driver has no liability insurance or not enough of it. UM coverage also protects against underinsured motorists whose policy limits fall short of your actual damages.
-
Uninsured motorist coverage is not required in Louisiana-drivers can reject it on the state-prescribed form-but it is highly recommended. Declining UM coverage leaves you financially vulnerable if you are hit by one of the many uninsured drivers on the road.
-
UM can also address certain hit-and-run situations. However, Louisiana law may require corroborating evidence from an independent witness if there is no physical contact with the other vehicle, so documenting the crash and gathering witness details is critical.
-
Shreveport drivers who regularly travel at night, use busy corridors, or share vehicles with teen drivers should think carefully before lowering or rejecting UM coverage.
-
Call the agency to review your current declarations page and UM selection form so you understand exactly what protection you have today.
Driving Between Shreveport, Bossier City, Texas, and Arkansas
Many Shreveport residents routinely cross the Red River into Bossier City-a separate city, not a Shreveport neighborhood-for work or shopping, and also take weekend trips west on I-20 to Texas or north toward Arkansas.
-
Ordinary travel to other Louisiana cities or neighboring states usually remains within the standard coverage territory of a Louisiana private-passenger car insurance policy. R.S. 32:900 specifies coverage “within the United States of America or the Dominion of Canada.” But policy wording and exclusions always control.
-
List the address where the vehicle is principally kept. It may differ from your mailing address or workplace, particularly during an extended assignment away from Shreveport. Explain that arrangement accurately; misstating garaging information can affect premiums, underwriting or a claim.
-
Regular business use-delivery driving, rideshare, or frequent job-site visits-may not be fully covered by a personal auto policy, even if most miles are local. Disclose these patterns to your local agent.
-
Longer-term relocation, such as moving full-time to Dallas while keeping Louisiana plates, may require reviewing registration and insurance obligations in both states rather than assuming one policy fits all.
-
Call before a major change-a months-long work assignment in another state, or leaving a vehicle parked long-term at a relative’s home in a different city-so the policy can be adjusted if needed.
Regional Travel, Road Trips, and Policy Details Shreveport Drivers Should Check
For regional travel using I-20, I-49 and connecting roads, review your route before departure and disclose the actual mileage and vehicle use to your insurer. Trips to Baton Rouge, Texas or Arkansas can raise practical questions about towing distance and transportation after a loss without automatically requiring a different policy.
-
Most standard Louisiana policies cover personal road trips within the U.S. and sometimes Canada, but not every policy extends to business deliveries or commercial hauling.
-
Verify who is listed as a driver. Visiting family members or college-age children who take the car out of town may need to be added. Teen drivers who commute or travel frequently can affect premiums significantly.
-
Confirm liability limits, comprehensive and collision deductibles, and whether glass claims-like windshield chips from long interstate drives-are subject to a separate deductible.
-
Review rental reimbursement limits before a road trip so you know the daily dollar cap and total days covered if a collision away from home disables your vehicle.
-
Before a long multi-state trip, ask the agency to review your coverage. Discuss roadside or towing options if you do not already have them, confirm availability and any waiting period, and verify when a change would take effect.
Roadside Assistance, Towing, and Rental Cars for Shreveport Commuters
Breakdowns happen-on I-20, along Youree Drive during slow traffic, or on a rural Caddo Parish highway with no services nearby.
-
Roadside plans may include towing, jump-starts, fuel delivery, flat-tire help and lockout assistance. Check the specific services, towing destination or mileage cap, service-call limits, reimbursement process and excluded costs in your plan.
-
Towing distance limits matter. You might prefer your trusted Shreveport mechanic over the nearest small-town garage, but exceeding the towing distance in your policy can leave you with out-of-pocket costs.
-
Rental reimbursement coverage typically has a daily dollar limit and a maximum number of covered days. If your vehicle is in a body shop for collision repairs far from home, those limits determine how long you can keep a rental without paying the difference.
-
Some policies reimburse for rideshare or public transit instead of a traditional rental car. Coverage only applies after a covered claim, not during routine maintenance.
-
Towing and rental reimbursement address different situations. Roadside assistance may help after a covered breakdown; ordinary rental reimbursement generally requires a covered insured loss and does not automatically pay for a rental during mechanical repairs. Confirm any separate mechanical-breakdown benefit rather than assuming it is included.
What to Do After a Crash Away From Home
Shreveport residents are sometimes involved in collisions while visiting relatives in another parish, driving to a game in Dallas, or returning from a trip along I-20 or I-49.
-
Move to safety if possible. Call 911 for injuries or immediate danger, follow the dispatcher’s instructions, and comply with the crash-reporting requirements where the incident occurred. Do not assume police will attend every minor collision.
-
Exchange information with all involved parties: names, phone numbers, license plate numbers, insurance company and policy numbers. Take clear photos of other vehicles, your vehicle, surroundings, and road signs.
-
Obtain contact details for independent witnesses. This is especially important for potential uninsured driver or hit-and-run situations, where a police report and witness corroboration can directly affect an uninsured motorist claim.
-
Call your insurer’s claim line from the scene if it is safe. Contact Louisiana Car Insurance at (844) 454-1313 as soon as practical for help understanding next steps and coverage.
-
Official resources for road conditions and nonemergency concerns: Louisiana 511 for statewide road conditions, Shreveport Traffic Advisories for local updates, and the city’s Report-A-Concern portal for nonemergency road issues.
Pre-Trip Car Insurance Checklist for Shreveport Drivers
Before a weekend in Dallas, a family visit in Arkansas, or a long in-state drive, run through this quick checklist.
-
✅ Confirm your insurance ID card is current, stored in the vehicle and on your phone, and that the VIN and license plate numbers match the car you are actually driving.
-
✅ Review liability, collision, and comprehensive coverage. Verify deductibles and consider adjusting if the vehicle has increased in value or is now financed or leased.
-
✅ Double-check who is allowed to drive the vehicle on the policy, including teen drivers home from college or relatives who will share the driving on a long route.
-
✅ Verify roadside, towing, and rental reimbursement limits. Add them before departure if needed-especially if you would want towing from a different city back to a trusted Shreveport repair shop.
-
✅ Save key phone numbers into your phone: your carrier’s claims line, Louisiana Car Insurance at (844) 454-1313, and any roadside assistance numbers.
How to Compare Car Insurance Rates and Coverage in Shreveport
Car insurance rates in Shreveport, LA vary by driver, vehicle, and coverage choices. Comparing quotes is about more than picking the lowest premium.
-
Focus on comparing liability limits, UM coverage, comprehensive and collision deductibles, and any exclusions that affect regional travel or business use. Rates for car insurance vary significantly by provider in Louisiana.
-
Gather your current declarations page, driver’s license numbers, vehicle identification numbers, and estimated annual mileage before calling for quotes.
-
Factors that influence premiums include prior accidents, tickets, teen drivers in the household, vehicle type, age, and garaging ZIP codes within Shreveport and Caddo Parish. Louisiana law restricts lapse-based pricing and eligibility decisions, including protection for a qualifying first lapse of 90 days or less. See our cost guide for protections and exceptions. A clean driving record can significantly reduce car insurance premiums.
-
Compare quotes using the same driver information, vehicle, liability limits, UM choices, deductibles and policy term. A statewide average from an agency page is not a Shreveport-specific quote, and figures from different studies may use different driver profiles. Review the actual offered premium, installment charges and total term cost before choosing.
-
Ask about available multi-policy, low-mileage and vehicle-safety discounts and what documentation is needed. Savings percentages and mileage thresholds vary by insurer; driving fewer than a particular number of miles does not automatically qualify you. Compare the final combined cost and coverage when bundling policies, and review information collected by any usage-based program.
-
Request a quote online to get started. Call (844) 454-1313 with questions, and use our car insurance quotes guide to prepare. This page describes the Shreveport service area, not a local walk-in office. A request does not bind coverage.
Special Situations: Teen Drivers, SR-22 Filings, and Non-Owner Options
Some Shreveport drivers face more complex situations-adding a teen driver, needing an SR-22, or driving regularly without owning a car.
-
Teen drivers in Shreveport and Caddo Parish typically mean higher premiums. List them correctly on the policy and consider the extra value of UM, collision, and comprehensive coverage when new drivers use family vehicles.
-
Some drivers may be required by Louisiana OMV to file an SR-22 certificate after certain violations. An SR-22 is a filing tied to a qualifying auto policy-not a separate type of insurance. Learn more at our SR-22 insurance page.
-
A non-owner policy with an SR-22 filing may be an option for an eligible driver without a vehicle. Regular access to a household car can affect eligibility. Disclose owned and regularly used vehicles, and confirm the filing requirements with OMV; buying a policy or filing alone does not reinstate a license.
-
SR-22 requirements and duration are determined by Louisiana OMV, not by the agency. Confirm your specific obligation directly with the state before choosing coverage.
-
If you fall into any of these categories, call (844) 454-1313 for a one-on-one review. Misunderstandings about teen drivers or SR-22 obligations can lead to costly gaps and money wasted on the wrong policy.
Frequently Asked Questions About Car Insurance in Shreveport, LA
Below are answers to common questions from Shreveport and Caddo Parish drivers.
Do I need to change my car insurance if I move to a different neighborhood in Shreveport?
Yes. Update your garaging address any time you move, even within Shreveport or Caddo Parish, because ZIP codes and overnight parking situations can affect car insurance rates and coverage assumptions. Staying within Louisiana usually means you keep a Louisiana policy, but failing to report a new address could complicate a claim if your vehicle is routinely parked overnight in a different location than what your insurer has on file.
What if my car mostly sits parked while I commute with someone else?
Do not cancel required coverage simply because a vehicle is rarely driven. Confirm Louisiana registration and financial-responsibility requirements, any lender obligations and the protection needed while parked. Report a genuine mileage reduction and ask whether a discount is available; thresholds vary by insurer. Before driving again, confirm coverage is in force.
Am I covered when I rent a car for a trip out of Shreveport?
R.S. 22:1296 requires covered insurers to extend existing automobile coverages to rental vehicles and qualifying temporary substitutes. This does not create coverages you did not buy. Ask your insurer which limits and deductibles apply, how any separately purchased rental protection affects priority, and whether rental-company charges such as loss of use are covered before declining protection.
How does sharing a car with a roommate or relative across the Red River work?
The person who primarily owns and garages the vehicle-for example, at a Shreveport address-typically carries the policy. Regular drivers in both Shreveport and Bossier City should be disclosed to the insurer. Occasional borrowing is handled differently from regular shared use, so households with this arrangement should talk with an agent to make sure the correct drivers and addresses are listed and that any fault or claim is properly covered.
Can Louisiana Car Insurance still help me if I’ve had a lapse or a serious violation?
Absolutely. The agency works with Shreveport drivers who have had coverage lapses, at-fault accidents, or serious tickets and can help them understand their coverage options. Violations can affect premiums. Louisiana law limits lapse-based pricing and eligibility decisions, as explained above. Check any OMV notice for individual SR-22 requirements and review your situation with an agent. Call (844) 454-1313 to get started.
Shreveport Service Area
This map shows the Shreveport area served by phone. It does not identify a walk-in office.